A debt growth charts Template is most useful when it turns a collection of balances, payment records, dates, and interest rates into a visual story that can be understood quickly. Some readers want to monitor personal debt as it declines, while others want to study how a national or institutional debt balance changes over time. In both cases, the underlying principle is the same: organize consistent time-based data, select an appropriate chart, and make the movement of the balance easy to interpret.
Search interest around this topic also reflects several different practical needs. A person may want a spreadsheet dashboard, a printable worksheet, a historical chart, or a document suitable for a report. A well-designed template can accommodate these purposes without becoming unnecessarily complicated. The strongest designs separate raw debt information from visual summaries so that changes can be made without rebuilding every chart.
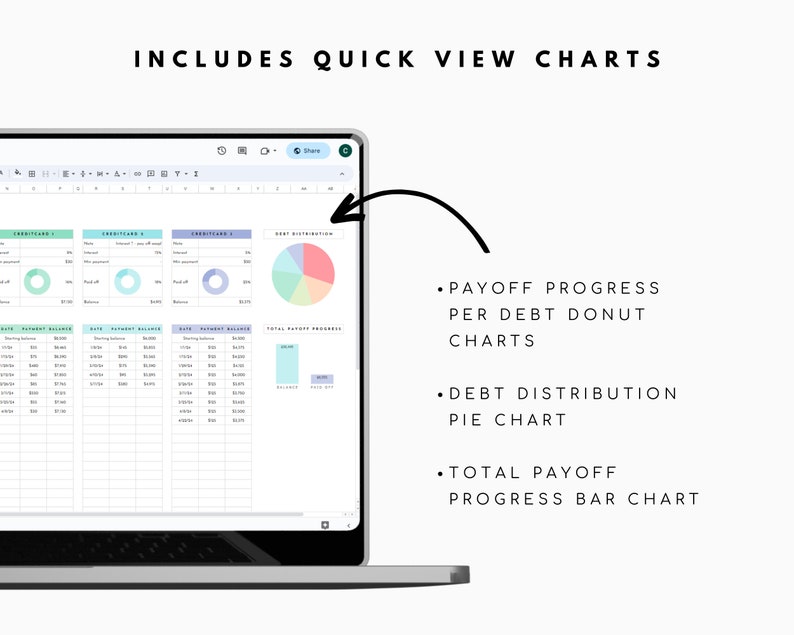
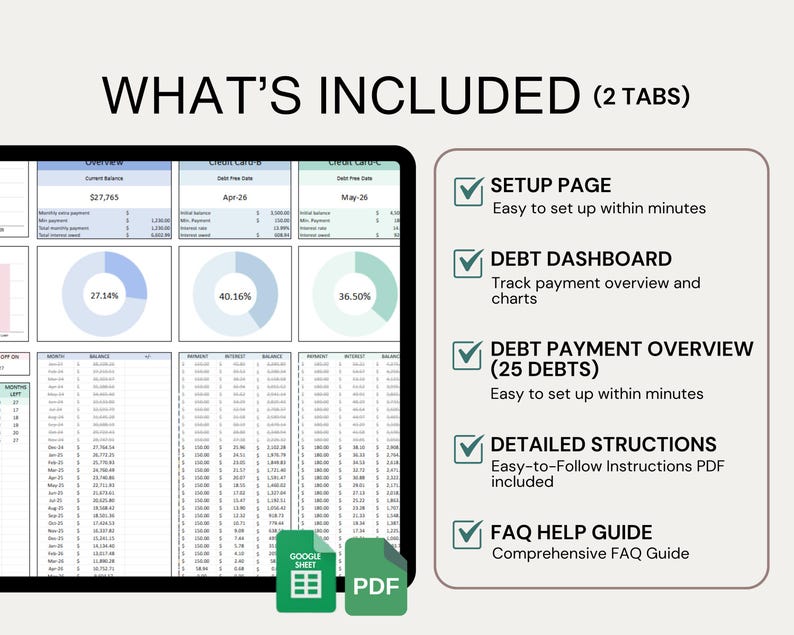
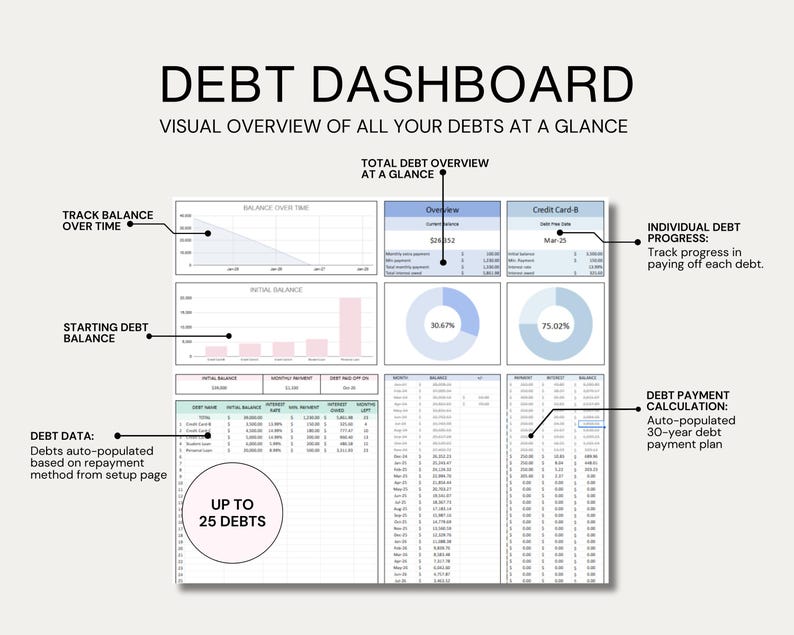
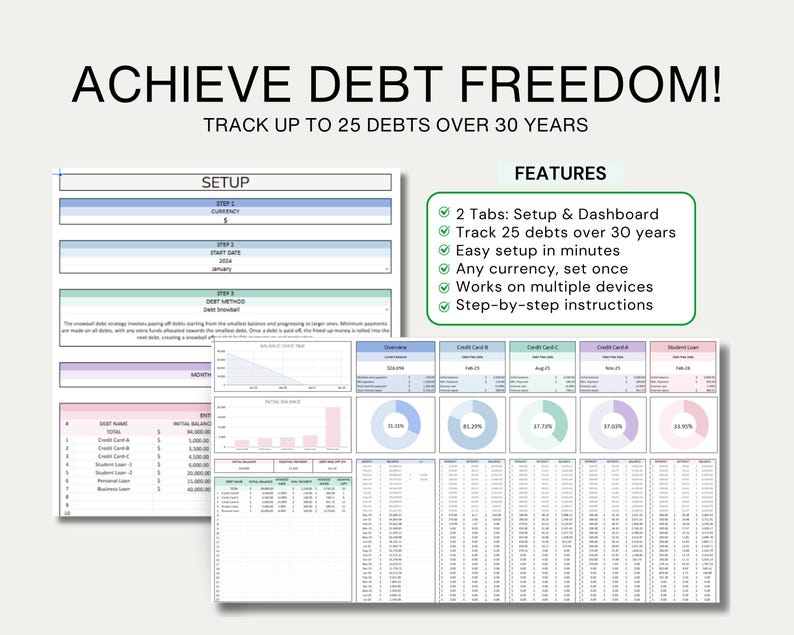
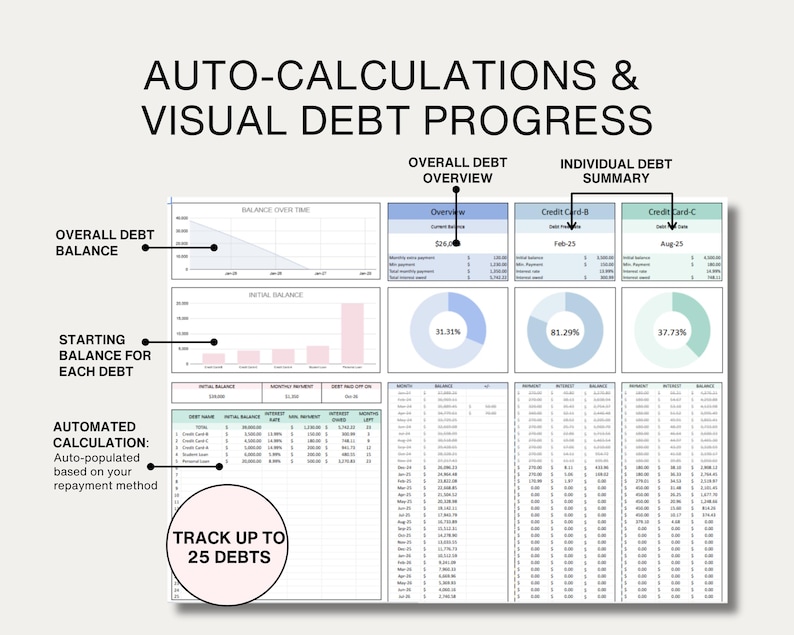
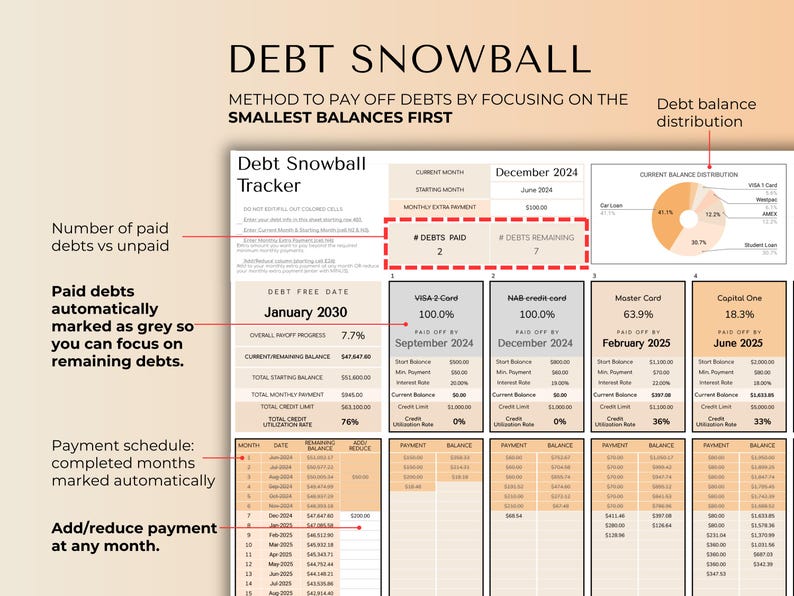
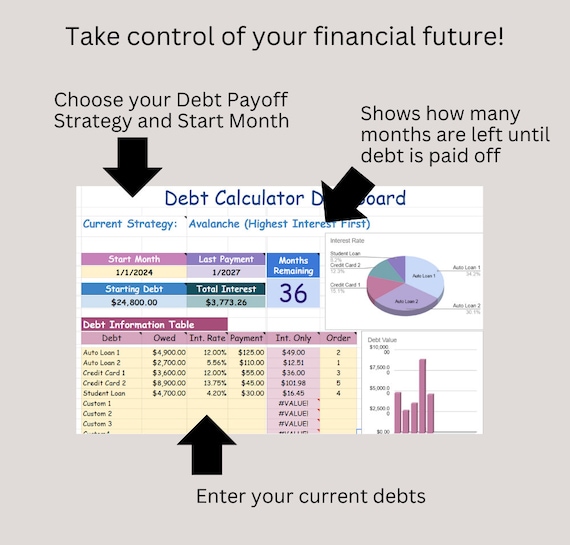
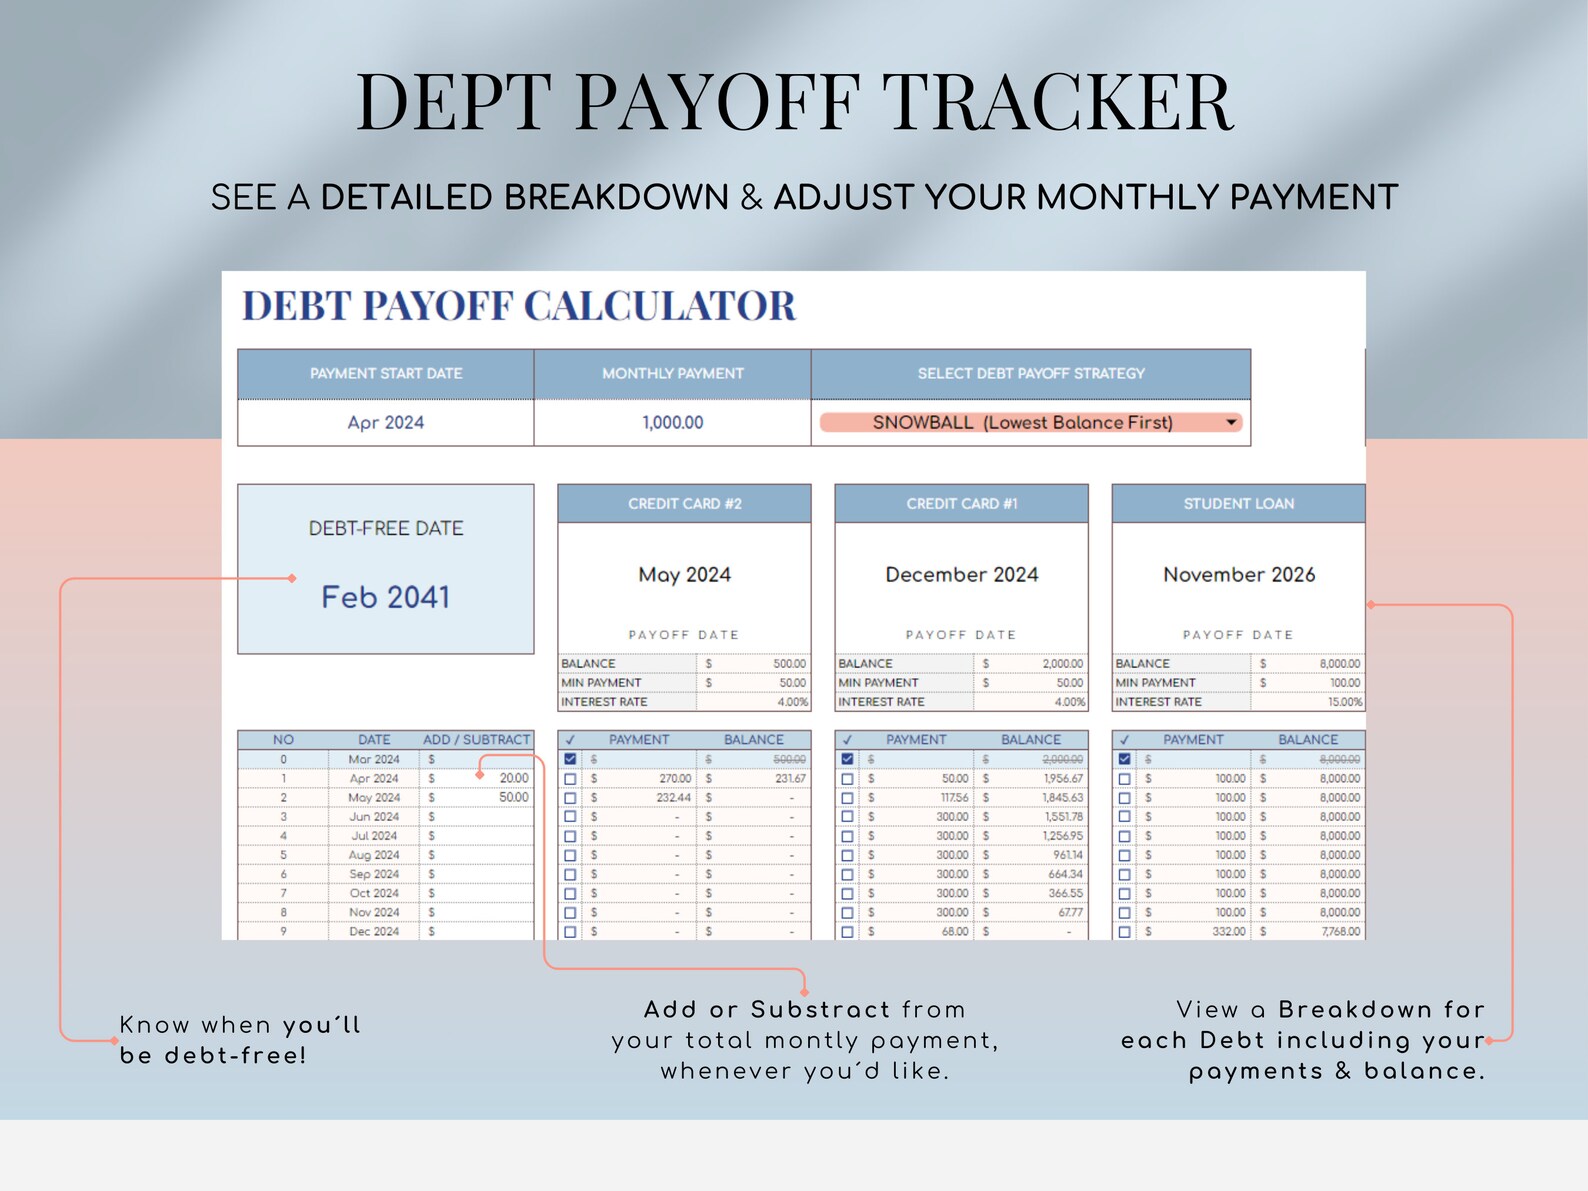
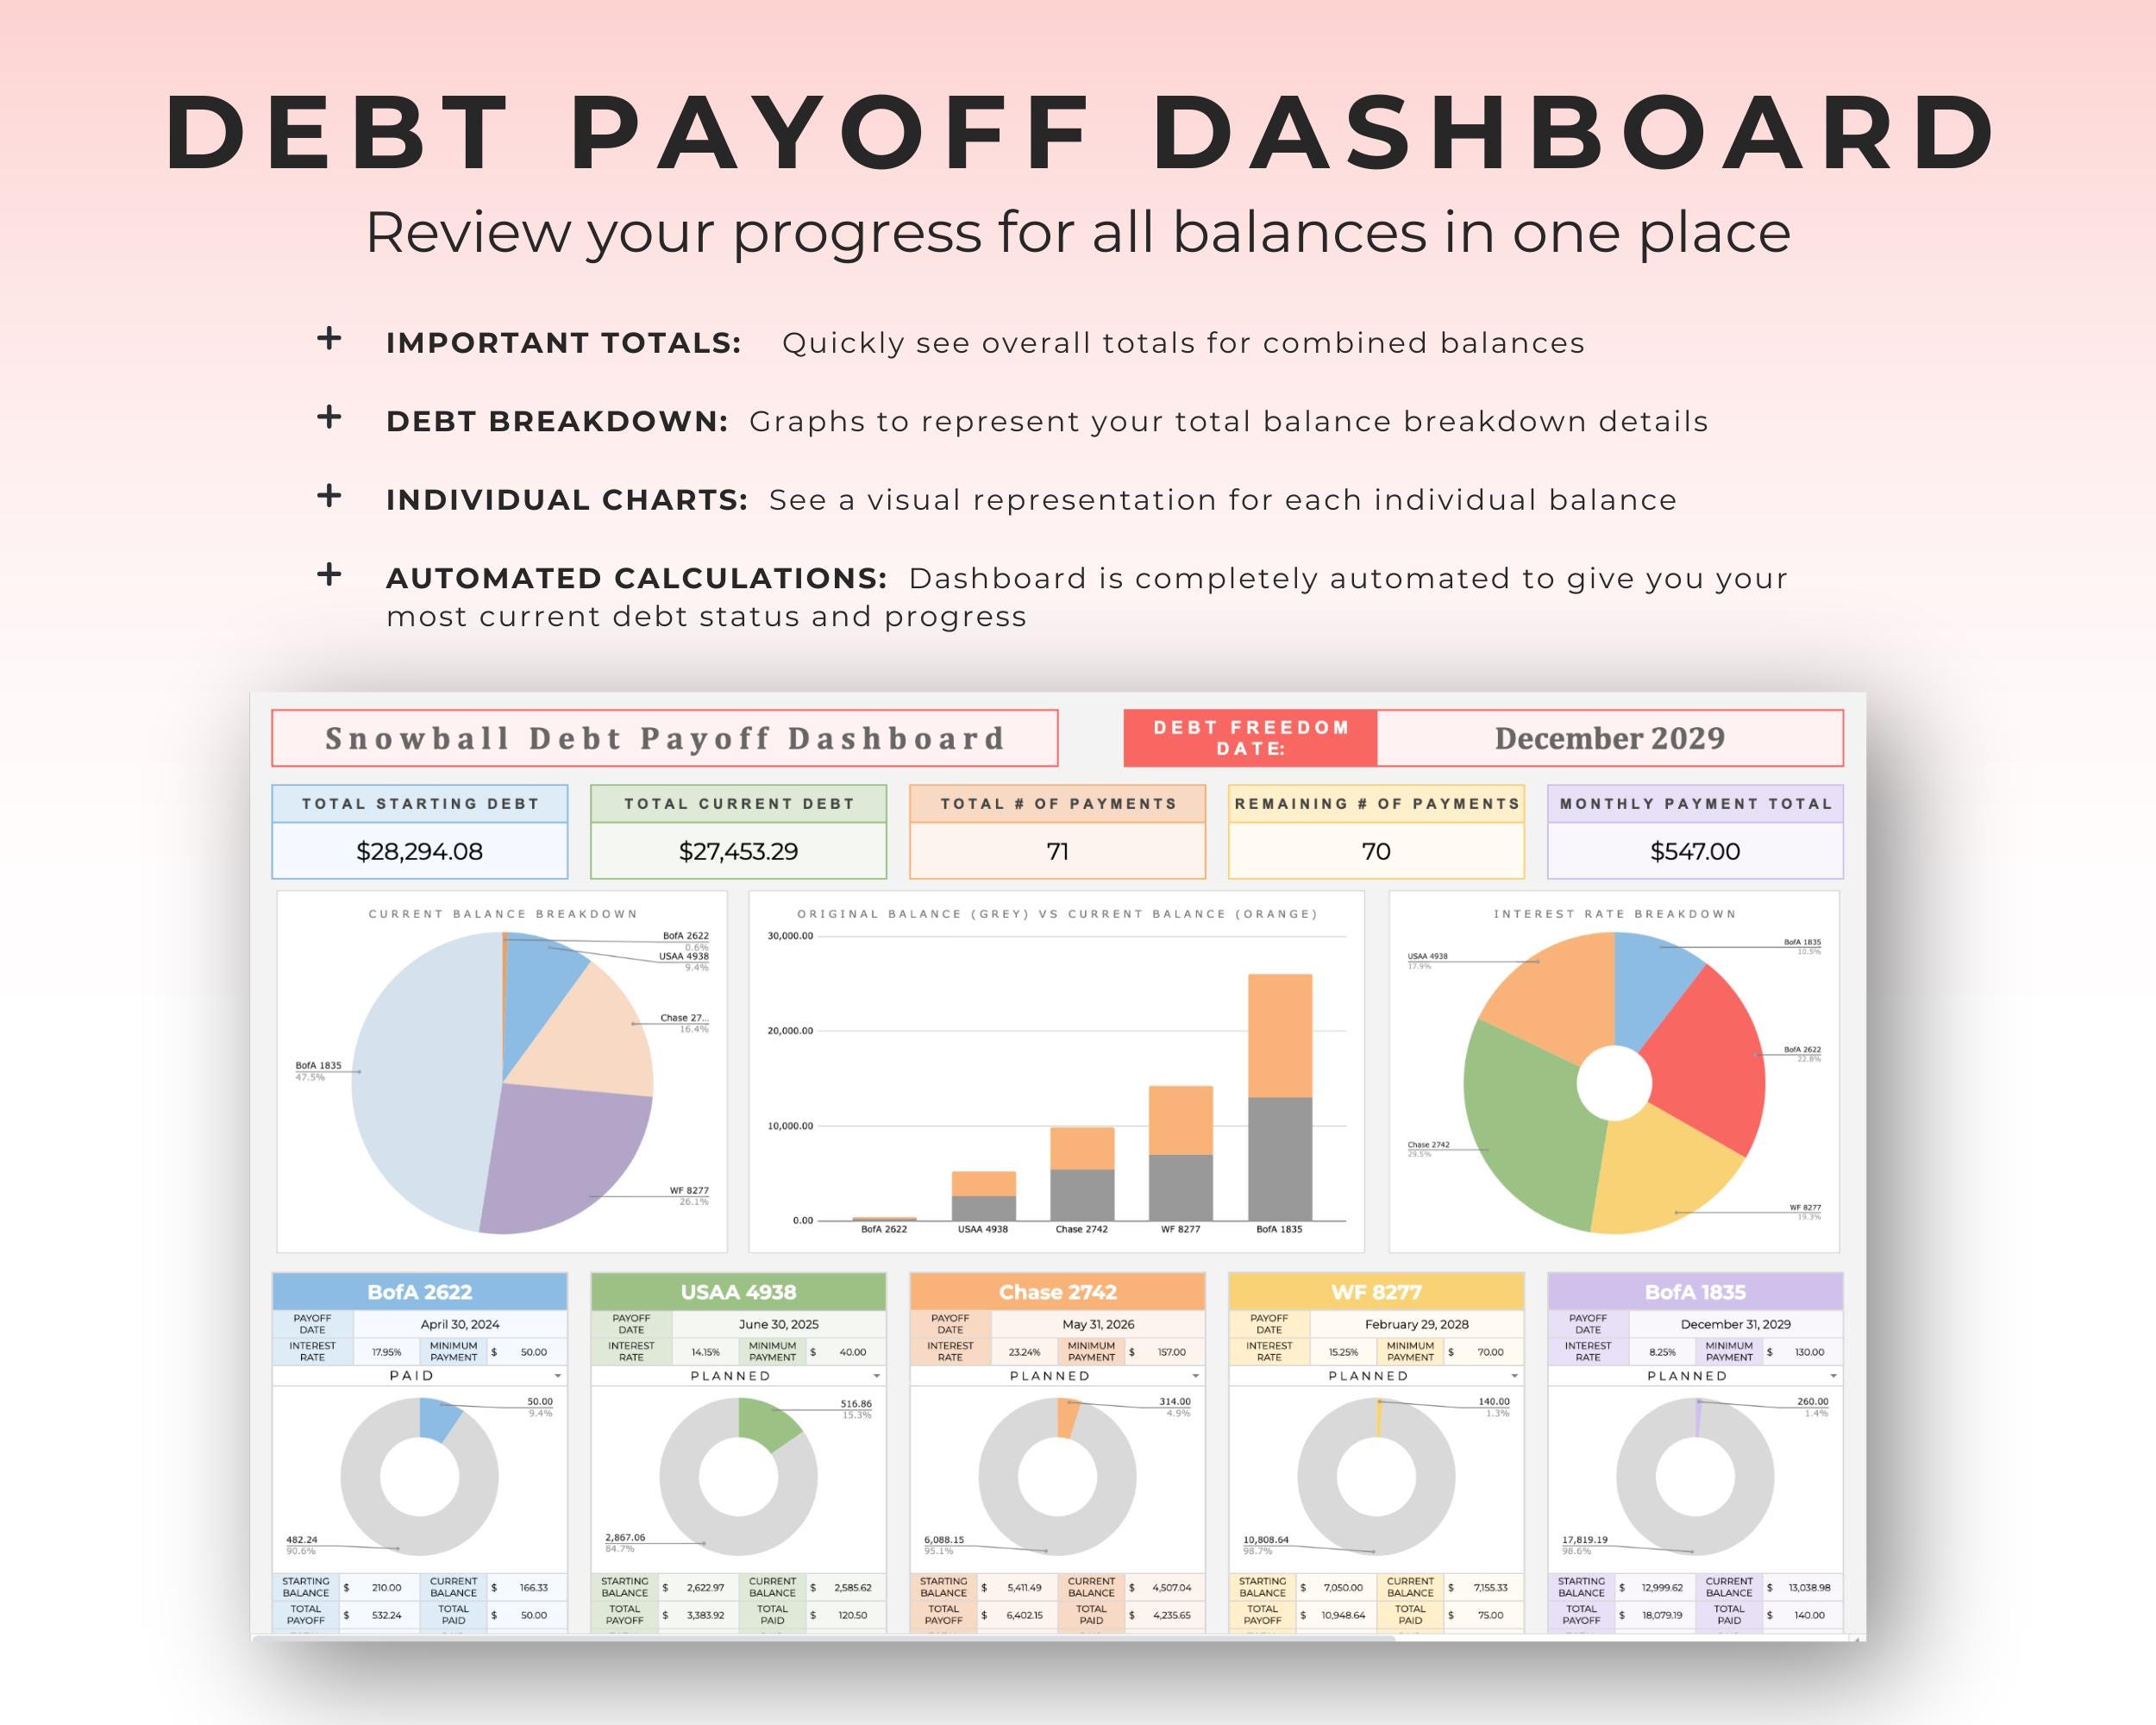
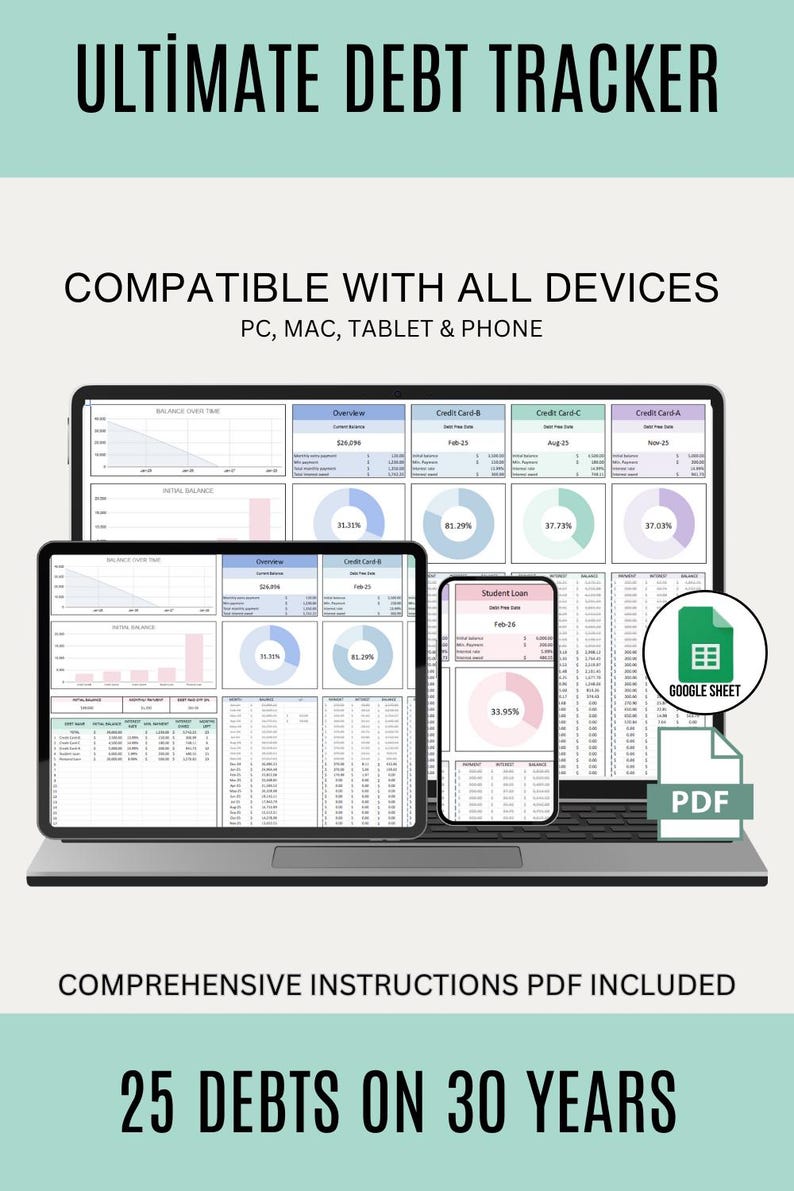
Current examples of debt trackers commonly combine a debt list, payment schedule, balance history, payoff projections, and visual progress indicators. Spreadsheet-based examples also demonstrate that a chart can compare starting balances, remaining balances, interest, and repayment periods in a single dashboard. :contentReference[oaicite:0]{index=0}
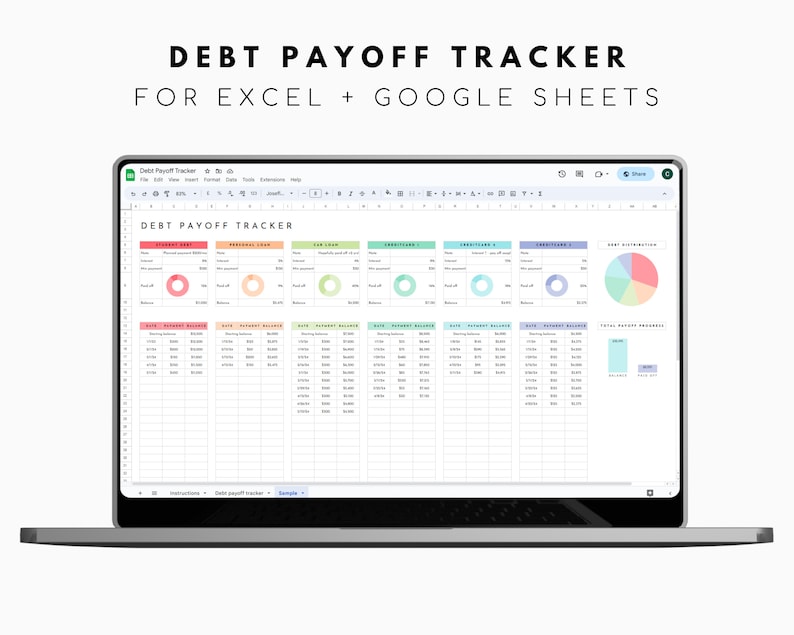
What a debt growth charts Template should actually show
The phrase can describe more than one kind of chart, so the first design decision is to establish what “growth” means in context. For a personal debt tracker, growth may refer to the historical movement of the outstanding balance before repayment begins, followed by a declining balance as payments are made. For national debt analysis, growth normally means the increase in total outstanding debt across years or decades. These are visually different stories even though both use time-series data.
A useful template therefore begins with a clearly defined measurement. A personal chart might use month on the horizontal axis and remaining balance on the vertical axis. A historical national debt chart might use year on the horizontal axis and debt measured in billions or trillions on the vertical axis. Mixing these definitions can create a misleading visual, especially when one chart compares nominal dollars with inflation-adjusted dollars.
The data layer should contain enough information to reproduce the chart without manual guesswork. Typical fields include date, creditor or debt category, starting balance, current balance, payment amount, interest rate, principal reduction, interest paid, and remaining balance. A historical public-debt dataset may instead contain year, total debt, debt held by the public, intragovernmental debt, or another clearly defined measure. Keeping the metric explicit is more important than adding decorative chart elements.
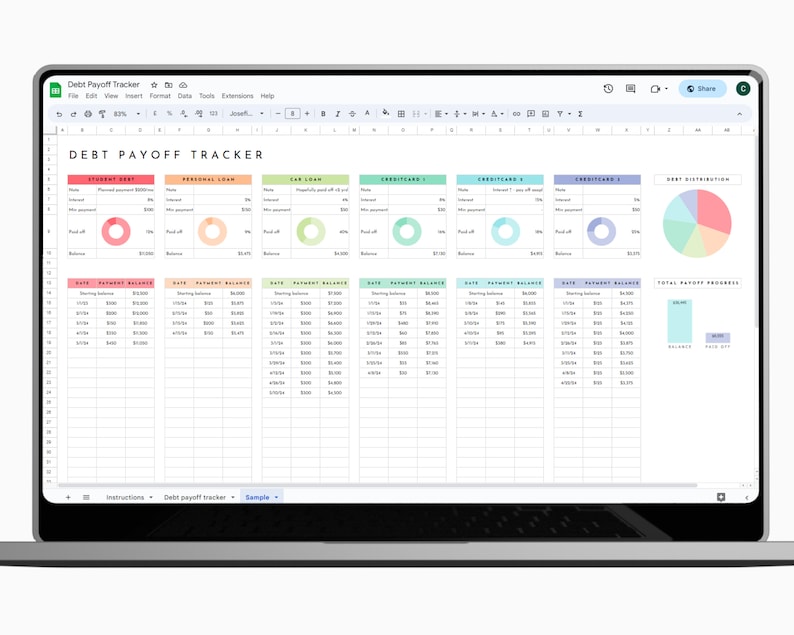
Separate the data from the visual layer
A dependable template should use one area for source data and another area for the finished visualizations. This structure makes it possible to add a new monthly observation, correct an earlier balance, or change a repayment assumption without manually editing the chart. It also makes the template easier to audit because every plotted value can be traced back to a specific record.
For a personal debt model, the source sheet can contain one row per month for each debt. A compact structure might include Month, Debt Name, Beginning Balance, Payment, Interest, Principal, and Ending Balance. If the chart is designed to show combined debt, an additional total column can sum the ending balances across all accounts for each month.
For a national debt chart, the structure should be even more disciplined. Historical values should use the same definition throughout the series, and the unit should remain consistent. A chart showing a century-long trend is only useful if readers know whether the amounts are nominal, inflation-adjusted, gross federal debt, or another defined measure. The U.S. Treasury is a primary source for federal debt data, while other reputable datasets visualize Treasury figures in different ways.
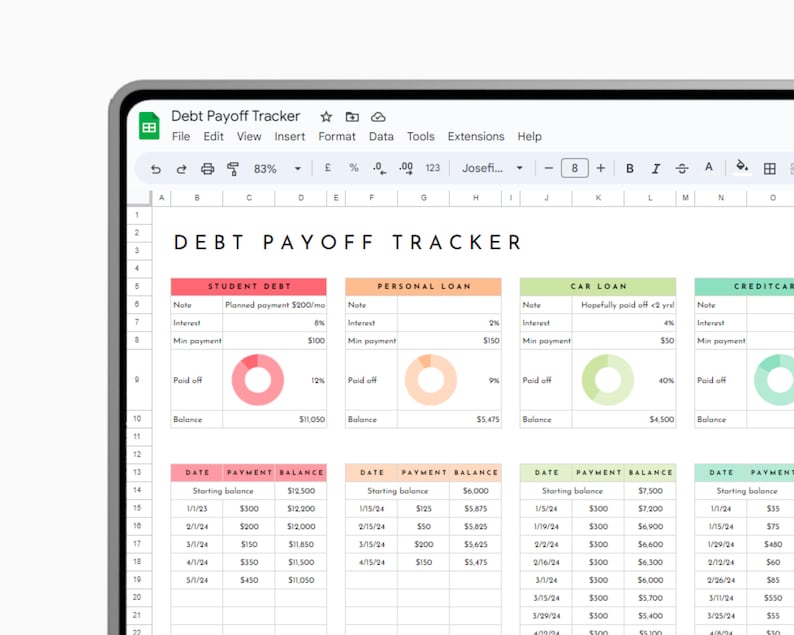
Choosing the right chart type
A line chart is usually the strongest choice when the main question is how debt changes through time. It makes direction, acceleration, plateaus, and turning points immediately visible. For a personal repayment plan, a downward-sloping line can show the expected reduction in outstanding debt. For a historical national debt series, an upward trend can reveal periods in which borrowing increased more rapidly.
A bar chart is useful when the purpose is comparison rather than continuous movement. For example, a dashboard can use bars to compare starting balances for credit cards, student loans, vehicle loans, and personal loans. It can also compare debt by year when the reader needs to distinguish individual periods rather than follow a continuous curve.
Pie or doughnut charts can help show composition, but they should be used carefully. They are appropriate when the question is how a total balance is divided among categories. They are less suitable for showing growth over time because a pie chart has no natural chronological axis. A strong dashboard can therefore use a line chart for the trend and a doughnut chart for the current composition.
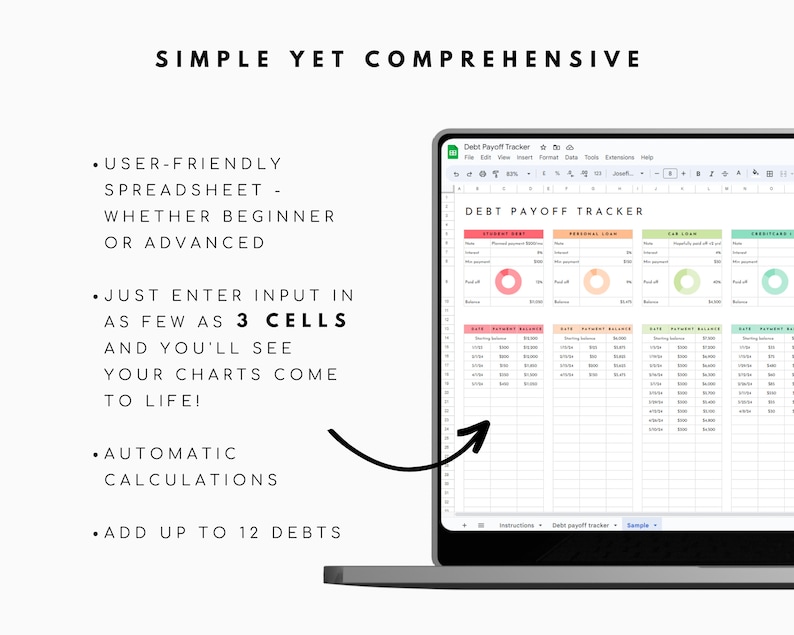
Use dashboards for multiple questions
A dashboard becomes valuable when several related questions need to be answered without opening multiple files. A good debt dashboard might place the total starting balance at the top, the current balance beside it, and the amount already repaid in another summary area. A trend chart can then occupy the largest space because it provides the most important visual context.
The next layer can show individual accounts. A bar chart can rank balances, while small progress charts can show how far each account has moved toward its target. This approach is particularly useful when a household has several debts with different interest rates and repayment dates.
Another useful dashboard element is a comparison between planned and actual progress. The planned series represents the original repayment schedule, while the actual series reflects what really happened. The gap between the two can reveal whether additional payments, missed payments, changing rates, or unexpected charges are affecting the plan.
Using Excel and Google Sheets for a debt chart
People searching for a debt growth charts template excel usually want a structured workbook that can store data and generate charts from the same source. Excel is particularly useful when the model needs formulas, multiple worksheets, scenario calculations, and a detailed historical record. A simple workbook can contain a data sheet, calculation sheet, dashboard, and assumptions area.
A debt growth charts template google sheets follows the same basic logic but is convenient when a document needs to be accessed through a browser or shared between people. The most important design principle is not the platform itself. It is consistency. The same debt definitions, dates, units, and formulas should be used regardless of whether the chart is maintained in Excel or Google Sheets.
For readers comparing a debt growth charts template excel free option with a more sophisticated workbook, the main question should be whether the structure matches the intended use. A simple tracker may be ideal for one or two debts, while a larger workbook may be preferable for many accounts, multiple strategies, historical reporting, and scenario comparisons. Current spreadsheet examples demonstrate both simple trackers and larger dashboards supporting numerous debts. :contentReference[oaicite:2]{index=2}
Core worksheet structure
The first worksheet should contain the raw debt information. Avoid mixing decorative graphics with the source table. A clean dataset makes later calculations much easier to inspect. Include one row per account or one row per account-period observation, depending on whether the workbook is designed around current balances or historical tracking.
The second worksheet can calculate monthly interest, principal reduction, and ending balance. A simplified educational example would begin with a hypothetical balance of $10,000, calculate interest for the period, subtract the principal portion of a payment, and carry the resulting balance into the next period. The example is illustrative rather than a forecast for any particular borrower.
The dashboard worksheet should contain only the information needed for interpretation. A reader should be able to identify total debt, current debt, percentage reduction, major balances, and the overall direction of the trend without scrolling through hundreds of calculation rows.
When a document format makes more sense
Some readers search for a debt growth charts template google docs because they want a narrative report rather than a calculation-heavy workbook. A document is useful when the chart will appear alongside explanations, commentary, definitions, and observations. The chart itself can be prepared from structured data and then placed into the report with a concise explanation of the metric and time period.
A document-based workflow can also be useful for classroom assignments, board reports, financial education materials, and research summaries. The important point is that the document should not become the source of truth for calculations. If the underlying data change frequently, the calculations should remain in a structured dataset or spreadsheet, while the document acts as the presentation layer.
Readers searching for a debt growth charts template pdf are often looking for a fixed-layout version suitable for printing or distribution. A PDF-style output is especially useful when the chart must preserve its formatting across devices. Before publishing a fixed version, verify that labels remain readable, the time axis is not crowded, and the units are clearly displayed.
How to build a chart showing debt growth by year
A reader searching for a chart showing national debt growth by year needs a historical series with one consistent observation for each year or another clearly defined interval. The first step is to choose the exact debt measure. “National debt” can refer to different measures, so the chart title should specify what is being measured and the source should identify the underlying dataset.
The second step is to organize the observations chronologically. If the data are annual, place the earliest year first and the latest year last. Avoid mixing fiscal-year figures with calendar-year figures unless the distinction is clearly explained. Once the series is consistent, plot the year along the horizontal axis and the debt amount along the vertical axis.
The third step is interpretation. A steepening line indicates faster numerical growth during that period, but the chart alone does not prove why the change occurred. Economic downturns, legislation, emergency spending, tax changes, interest costs, and other factors may contribute to changes in public debt. A responsible article should distinguish what the chart directly shows from explanations that require additional evidence.
Historical U.S. debt charts need careful labeling
A national debt growth chart can look dramatically different depending on the period and measurement selected. A short chart covering the last twenty years emphasizes recent acceleration, while a century-long chart provides a much broader historical perspective. Neither view is automatically better; the appropriate choice depends on the question the reader is trying to answer.
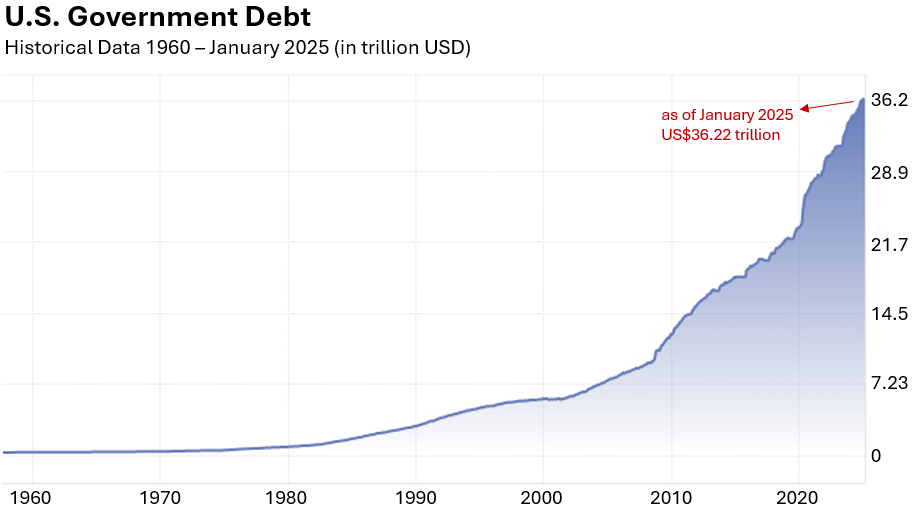
A us debt growth chart should also make its units visible. A graph using billions, trillions, or inflation-adjusted dollars can communicate the same broad trend while producing very different visual scales. For example, recent public charts have shown substantial long-term increases in U.S. debt, but the exact value represented depends on the date and debt definition used. :contentReference[oaicite:3]{index=3}
One useful practice is to place the data source directly beneath the chart in the finished report. Another is to include the date through which the data are current. This prevents readers from assuming that an older historical graphic represents today’s balance. A template should make these fields easy to update rather than burying them in small text.
Visual debt payoff charts for personal finance
A personal debt chart serves a different purpose from a national debt chart. Instead of explaining a macroeconomic trend, it helps an individual or household see progress against a repayment objective. The most useful designs normally track the remaining balance rather than simply adding up payments, because a payment may include both interest and principal.
This distinction matters when creating a visual tracker. Suppose a hypothetical debt starts at $12,000 and the borrower makes several payments. The total amount paid might be substantial, but the remaining balance is the more direct measure of how much debt is still outstanding. A template should therefore show both where useful, while keeping the remaining balance visually prominent.
Visual milestones can make long repayment schedules easier to understand. A chart may mark 25%, 50%, 75%, and 100% reduction points, or show the balance at the beginning and end of each quarter. These milestones do not change the financial calculation, but they can make progress easier to review during regular budget meetings.
Snowball and avalanche comparisons
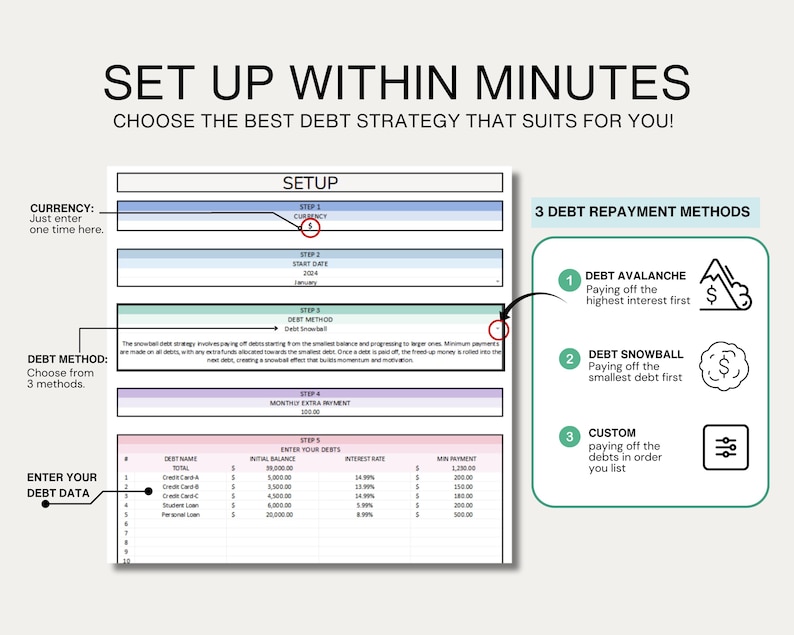
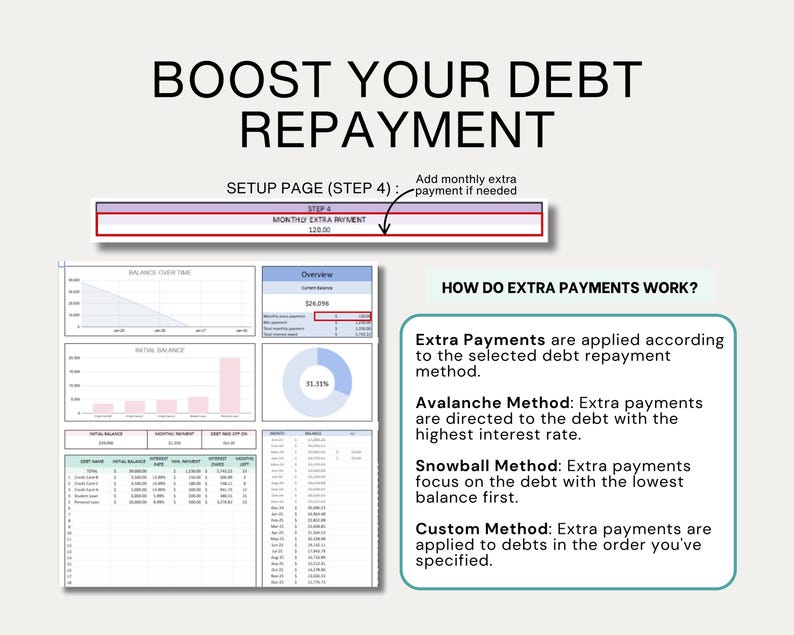
A debt snowball chart generally prioritizes debts from the smallest balance to the largest. Its visual appeal comes from showing individual accounts disappear as they are paid off. A debt avalanche chart instead prioritizes higher-interest debt first. The two methods can produce different intermediate paths even when the same total monthly payment is available.
A template that compares the two approaches should not hide the assumptions. Interest rates, minimum payments, payment timing, additional contributions, fees, and changing balances can all affect the outcome. A chart should therefore label a scenario as planned or projected rather than presenting it as a guaranteed future result.
For educational purposes, a comparison dashboard can show two lines on the same axes: one for the projected remaining balance under the snowball sequence and another for the projected remaining balance under the avalanche sequence. The visual difference becomes much easier to understand when the starting assumptions are identical.
Printable debt charts and worksheet layouts
Some people prefer a physical worksheet because writing down each payment makes the progress visible without opening a spreadsheet. A debt charts free printable search often reflects this preference for simple layouts with spaces for balances, payment dates, and milestones. A paper chart should prioritize legibility, enough writing space, and a clear sequence rather than complex calculations.
A good printable page can contain a debt name, starting balance, interest rate, minimum payment, payment date, payment amount, and remaining balance. If there are multiple debts, use separate sections or separate pages rather than squeezing too many columns into one sheet. The goal is to create something that can actually be updated comfortably.
Visual trackers can also use segmented bars, thermometers, grids, or milestone boxes. These designs are particularly useful when the reader wants a quick visual indicator instead of a detailed calculation model. Current examples of debt charts include worksheets that divide repayment into dated entries and balance checkpoints. :contentReference[oaicite:4]{index=4}
Using a debt growth charts Template for reporting
Reports benefit from charts that answer a specific question rather than displaying every available number. If the purpose is to show growth, emphasize the time series. If the purpose is to compare categories, emphasize the category chart. If the purpose is to explain repayment, emphasize the declining balance and key milestones.
For a professional report, keep the chart title descriptive. Instead of a vague heading such as “Debt Chart,” use a title that states the measure and period, such as “Outstanding Debt by Year” or “Projected Remaining Balance by Month.” A subtitle can provide the unit and source when necessary.
Annotations should be used sparingly. A few important dates can help explain sharp movements, but too many labels can obscure the trend. If a major event is relevant to interpretation, place a concise annotation near the relevant point and provide the fuller explanation in the surrounding paragraph.
Common mistakes when designing debt growth charts
One common mistake is using a chart that does not match the question. A pie chart cannot communicate a long-term trend as clearly as a line chart. A detailed monthly table may contain accurate information but still fail to reveal the direction of the overall balance. Choosing the visual first and the question second often produces clutter.
Another mistake is mixing incompatible measures. A chart should not quietly combine nominal debt values with inflation-adjusted values, or calendar-year observations with fiscal-year observations. If multiple measures are important, separate them into clearly labeled series or separate charts.
A third mistake is allowing the template to become visually overloaded. Too many colors, legends, labels, gauges, and decorative elements can compete with the actual data. The most effective debt dashboards usually have a clear hierarchy: headline metric, trend chart, account breakdown, and supporting detail.
Practical Solution
Start by defining the single question your debt growth charts Template must answer. If the objective is personal repayment, use remaining balance by month. If the objective is historical analysis, use debt by year. If the objective is category comparison, use account balances by debt type. This decision determines the data structure, chart type, labels, and level of detail.
Next, build a clean source dataset before designing the dashboard. Enter the debt name or category, observation date, balance, payment information, and any relevant rate or classification. Keep the original values separate from calculated fields. This creates a dependable foundation for Excel, Google Sheets, or a document-based reporting workflow.
Then create the visual layer. Use a line chart for change through time, bars for category comparisons, and a doughnut or pie chart only when composition matters. Add summary metrics such as starting balance, current balance, amount reduced, and projected payoff date where those values are supported by the underlying calculations. Do not display a projection as an observed fact.

Finally, review the chart as if you were seeing it for the first time. Can you identify the metric, time period, unit, and direction of change in a few seconds? Can you tell whether the values are actual, planned, or hypothetical? Can you locate the source and understand the assumptions? If not, simplify the design before publishing it.
For a debt growth charts template free download search, the same quality checks should apply as they would to a paid or custom-built template. A template is useful only when its calculations and definitions are transparent enough for the reader to understand. Likewise, a debt growth charts template free resource should be evaluated for structure and accuracy rather than judged solely by appearance.
How to make the template easier to maintain
Use consistent date formatting throughout the workbook. If monthly observations are used, every month should appear in chronological order. If annual observations are used, decide whether the year represents a calendar year, fiscal year, or another reporting period and state that clearly.
Keep formulas simple enough to audit. A complicated formula may save a few cells but make troubleshooting difficult. For personal repayment models, separate interest calculations, principal reduction, and ending balance calculations when possible. This makes it easier to identify why a balance does not match an external statement.
Use a version date on the dashboard when the chart represents changing information. Historical charts may remain stable, but current debt dashboards can change every month. A small “updated through” field prevents readers from confusing a historical snapshot with current information.
How to interpret growth without overstating the evidence
A rising line means the measured debt increased over the selected period. It does not, by itself, explain causation. A chart can reveal when the increase occurred, whether the slope changed, and whether there were periods of slower movement, but additional evidence is required to explain why those changes happened.
This distinction is especially important with national debt charts. A historical visualization can show large changes over decades, but it cannot independently establish the effect of a particular policy, recession, war, tax measure, or spending program. Those explanations should be supported by appropriate historical or economic sources.
Recent public visualizations illustrate why source dates matter. One chart from USAFacts shows U.S. national debt exceeding $38.5 trillion at the end of 2025 and separates total debt into debt held by the public and intragovernmental debt. A different chart may end earlier and therefore show a lower figure without either visualization being internally inconsistent.
Reference Examples
A debt growth charts Template can take many visual forms, but the strongest examples share a few characteristics: they identify the debt measure, organize observations chronologically, distinguish current balances from starting balances, and use charts that match the question being asked. Some examples emphasize individual account repayment, while others focus on national debt growth across decades. Looking at different layouts helps readers recognize which elements are essential and which are merely decorative. The most useful reference is not necessarily the most colorful design; it is the one whose structure makes the underlying numbers easy to understand and verify.
The following references illustrate practical approaches to the debt growth charts Template concept, including spreadsheet dashboards, repayment worksheets, historical national-debt graphs, progress trackers, and visual balance charts. They can help when deciding how much information belongs on one page, how to display a time series, how to separate categories, and how to make progress visible. When comparing examples, pay particular attention to axis labels, date ranges, units, balance definitions, and whether a chart represents actual historical data or a hypothetical repayment scenario.
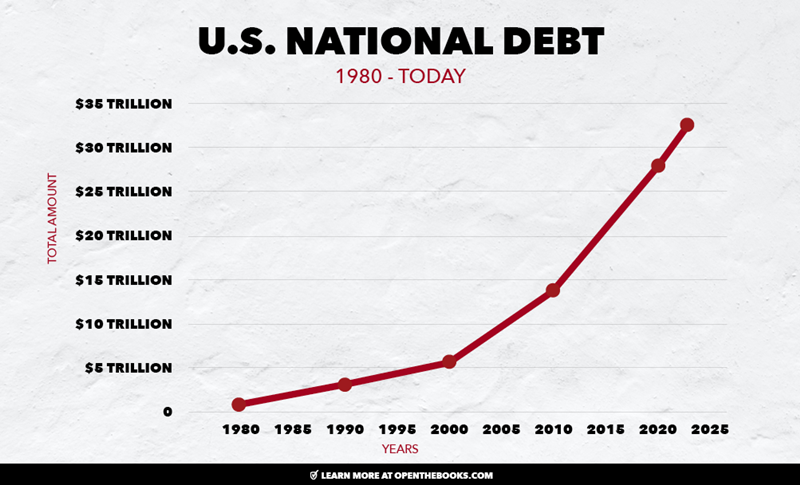
U.S. National Debt Growth Chart, 1980–Today
Source: OpenTheBooks
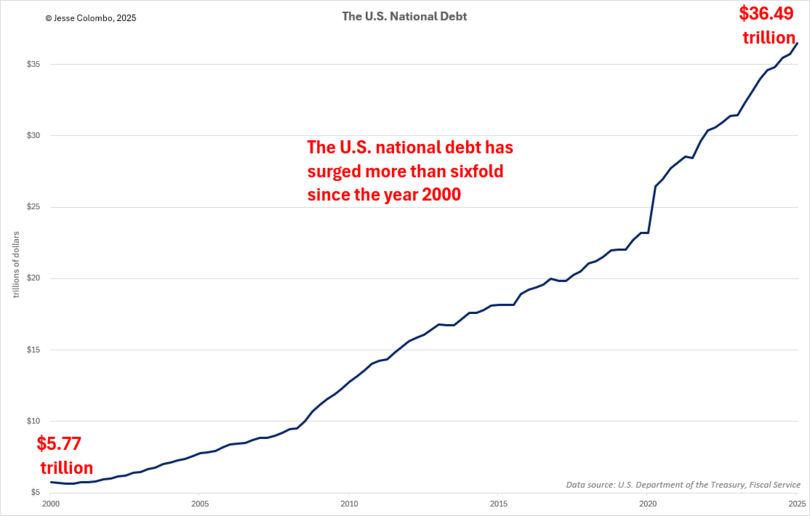
The U.S. National Debt, 2000–2025
Source: Money Metals Exchange
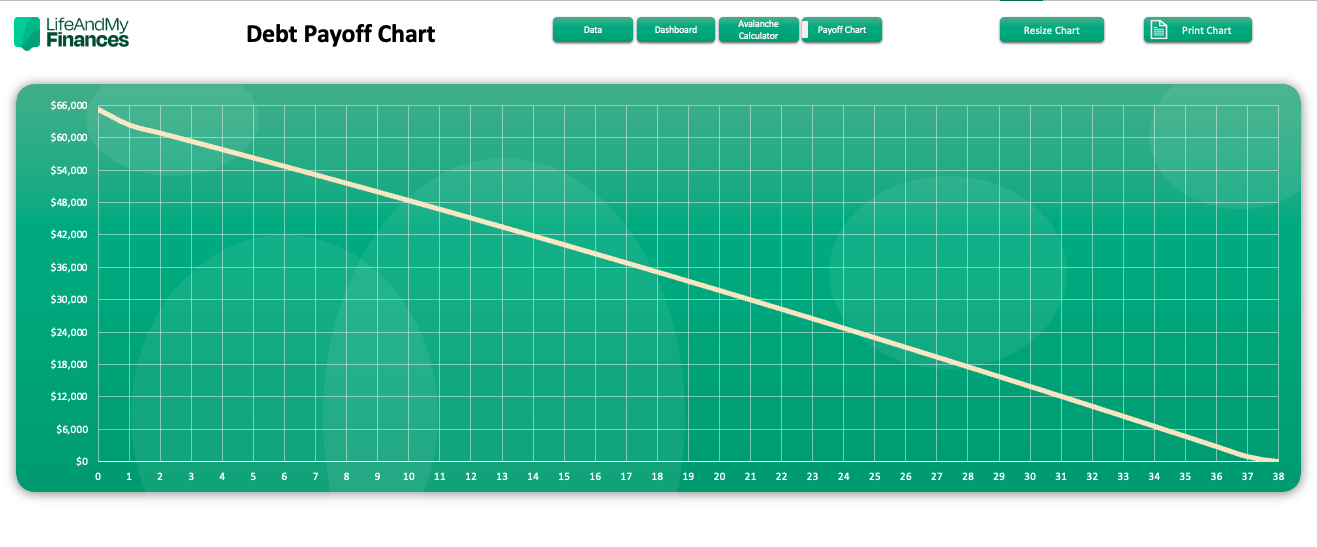
Debt Payoff Chart
Source: LifeAndMy Finances
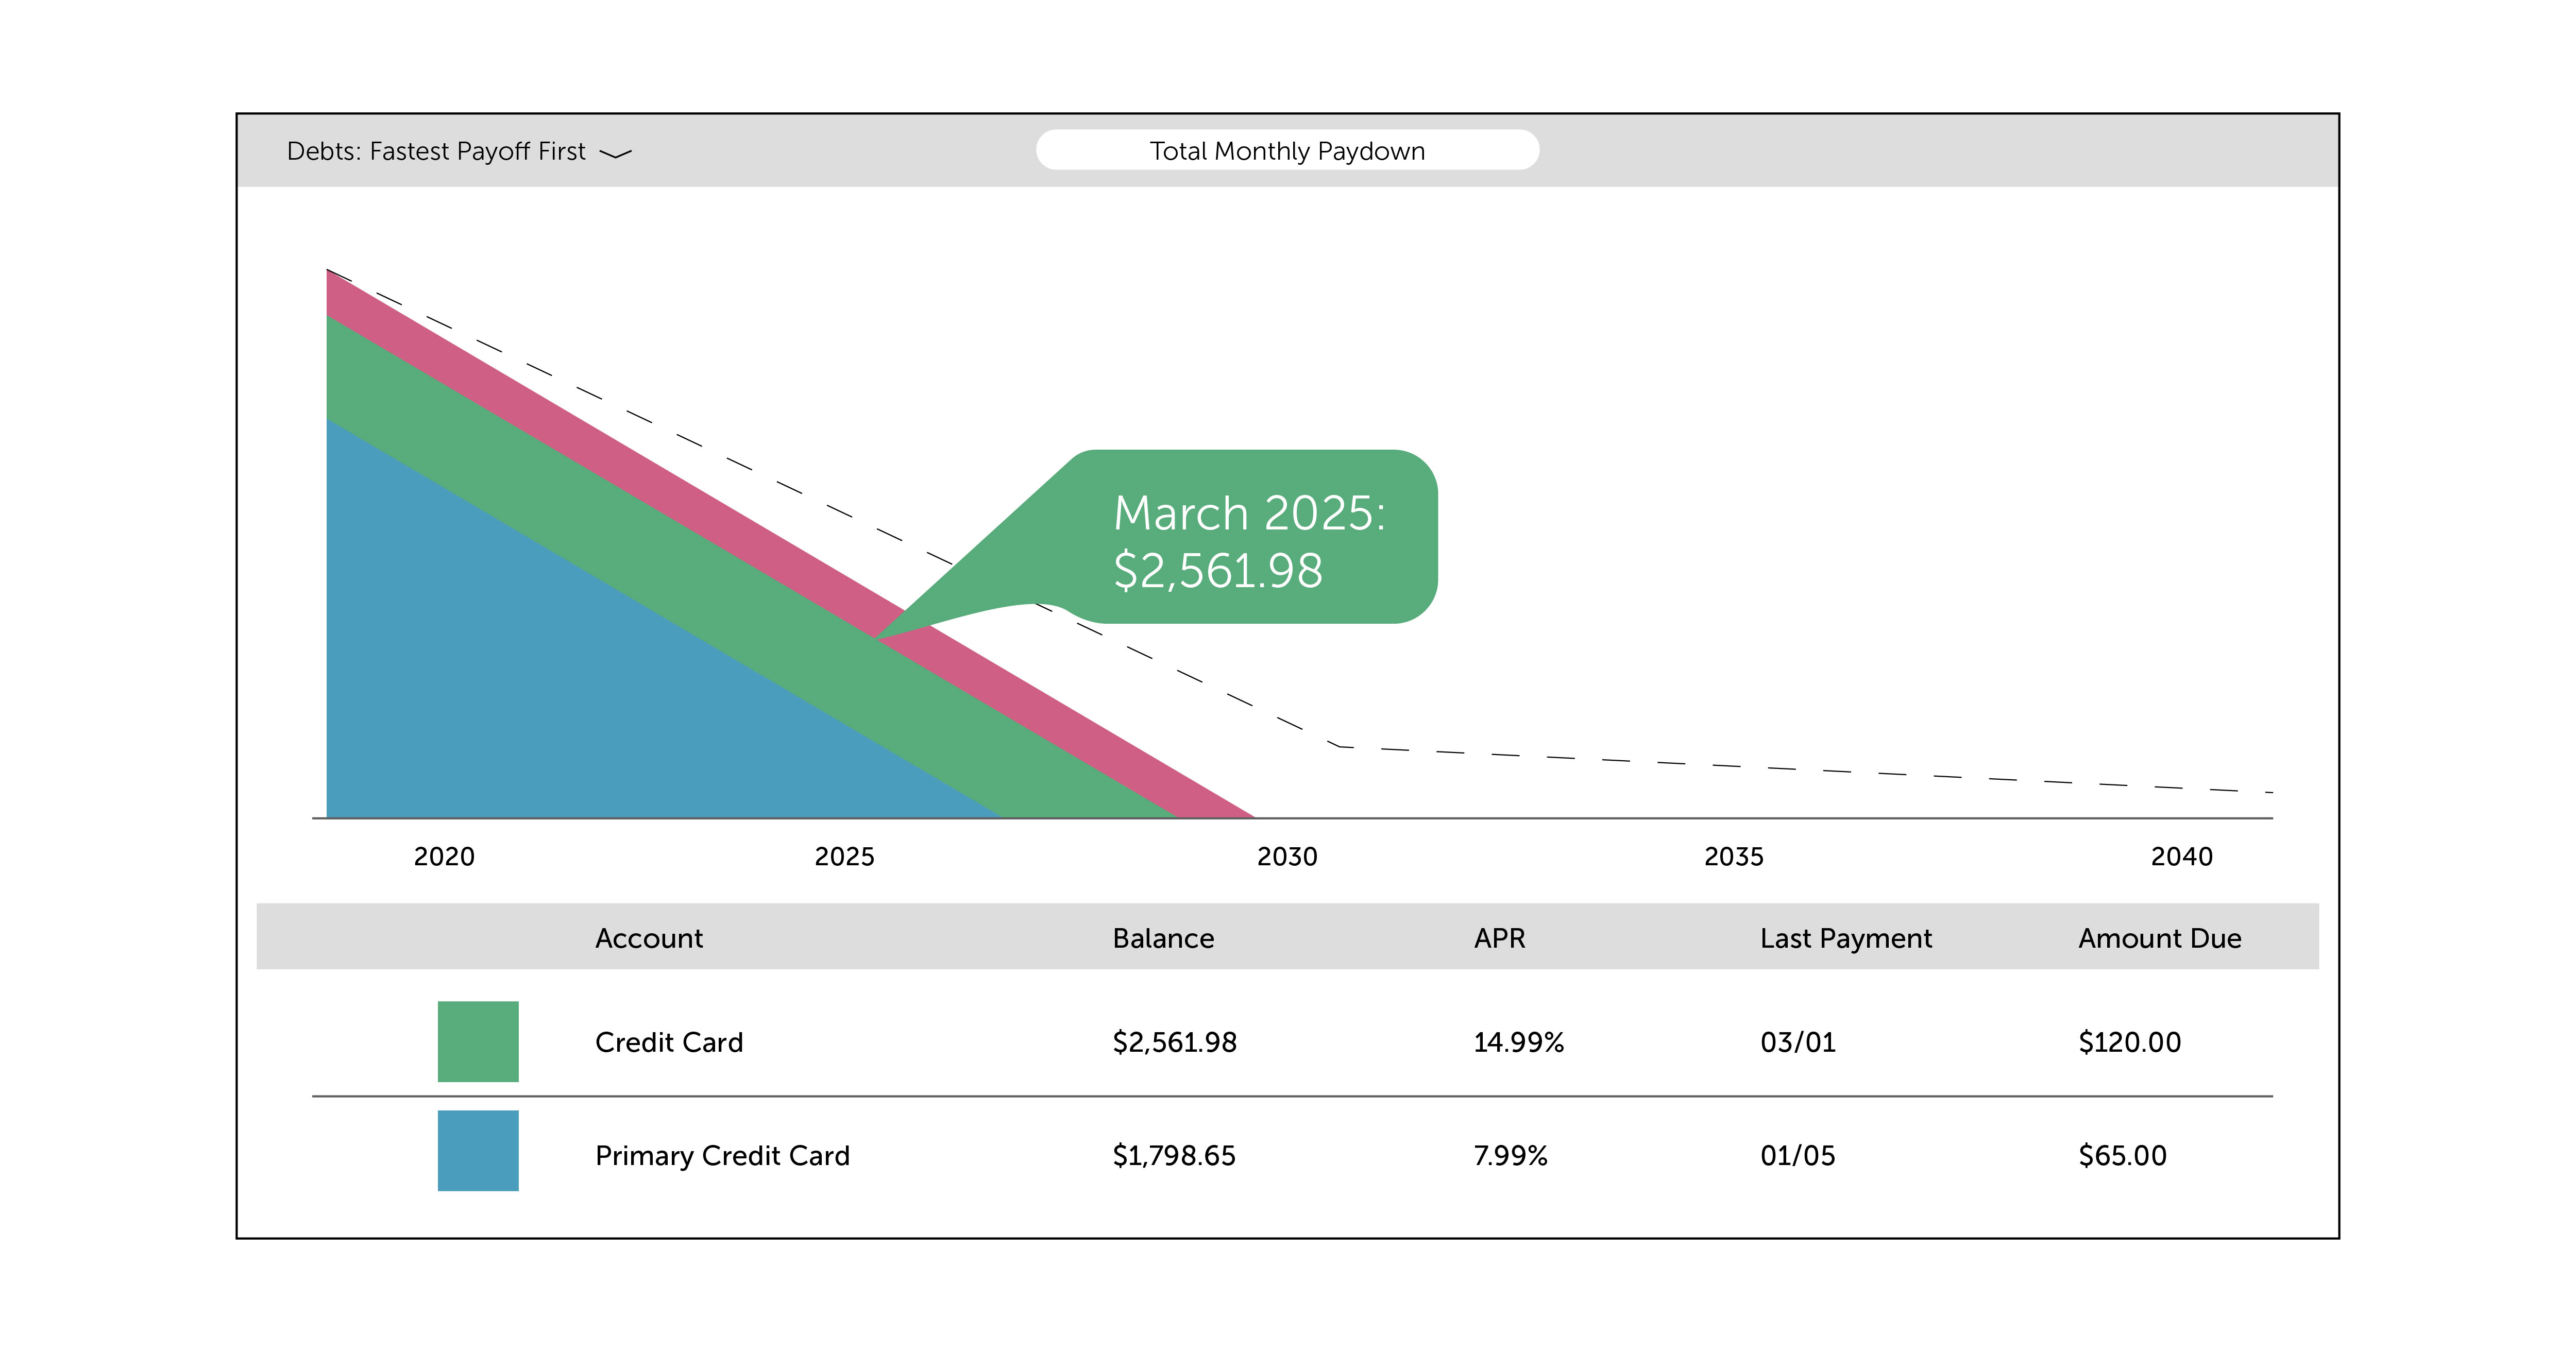
Financial Tools Debt Payoff Projection
Source: WestStar Bank

Minimalist Debt Snowball Tracker
Source: Mrs Neat
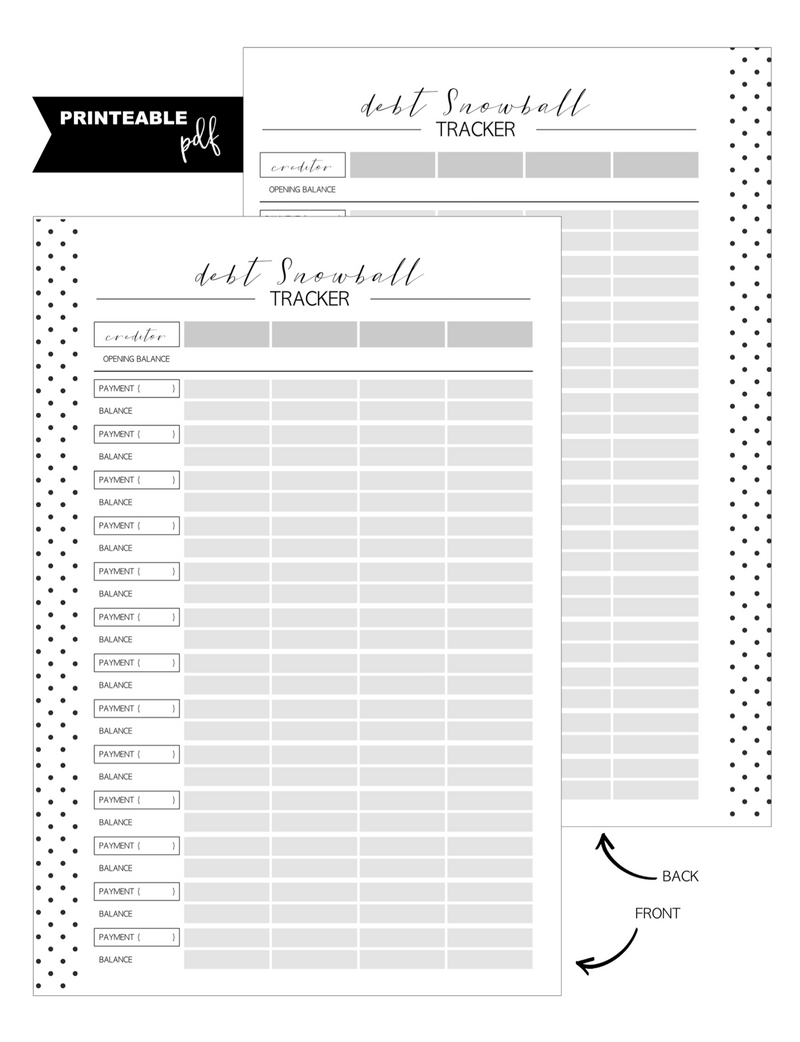
Snowball Debt Tracker Fill Paper
Source: Fancy Plans Co
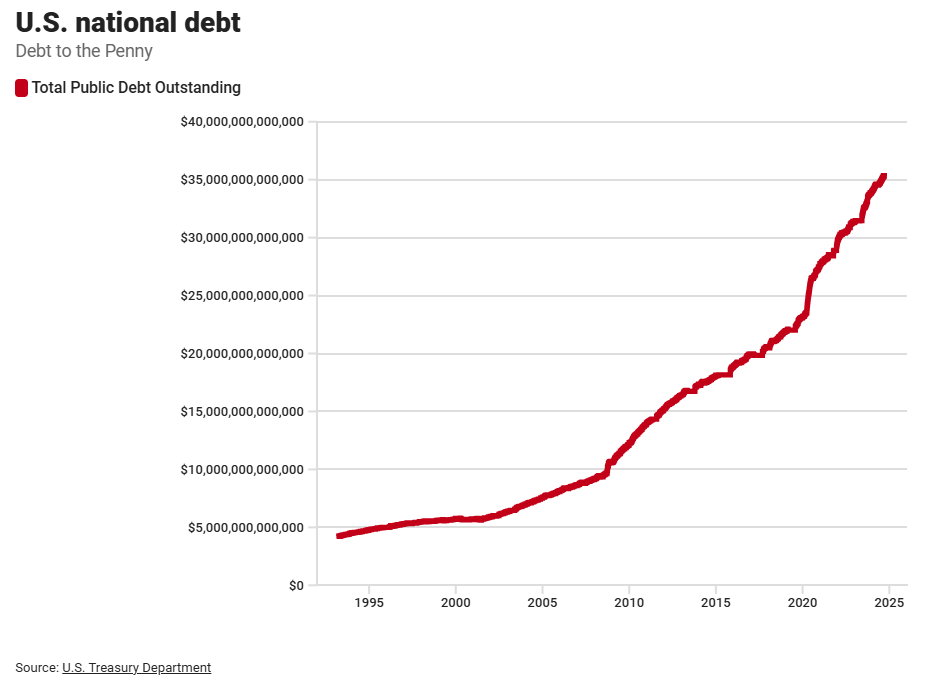
U.S. National Debt
Source: Crews Bank & Trust
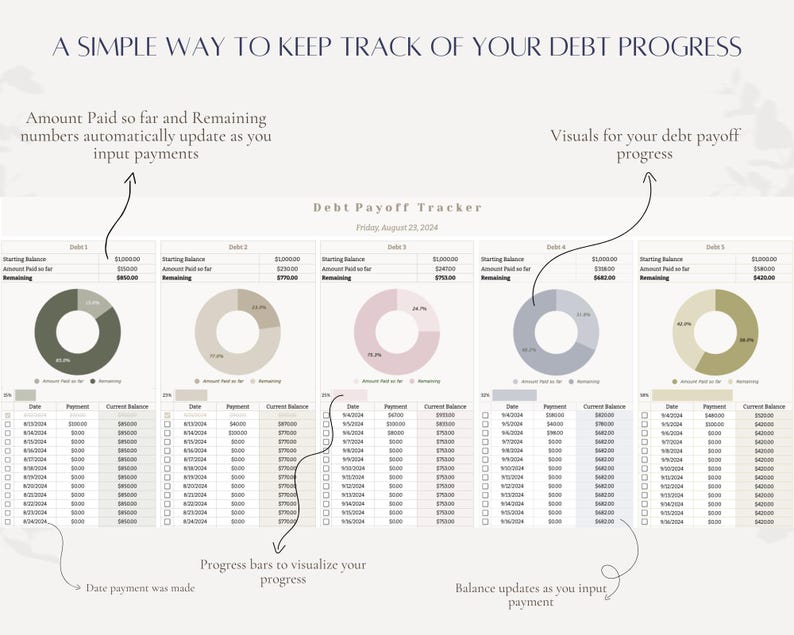
Debt Payoff Tracker
Source: Etsy
Debt Snowball Worksheet – Payoff Progress Tracker
Source: The Nomad Brad

Debt Management Setup Preview
Source: SpreadsheetsHub

Debt Spreadsheet Dashboard Preview
Source: SpreadsheetsHub

Debt Repayment Chart Preview
Source: SpreadsheetsHub
